HOA Winter Preparation: Getting Ready For Super El Nino In Colorado

With the cold season coming, HOA winter preparation becomes a priority. Due to the forecasted Super El Niño in Colorado, board members must adjust their typical routine to accommodate the shift. These adjustments can help ensure that the community and its residents are ready for what’s ahead.


How Super El Niño in Colorado Affects HOA Winter Preparation

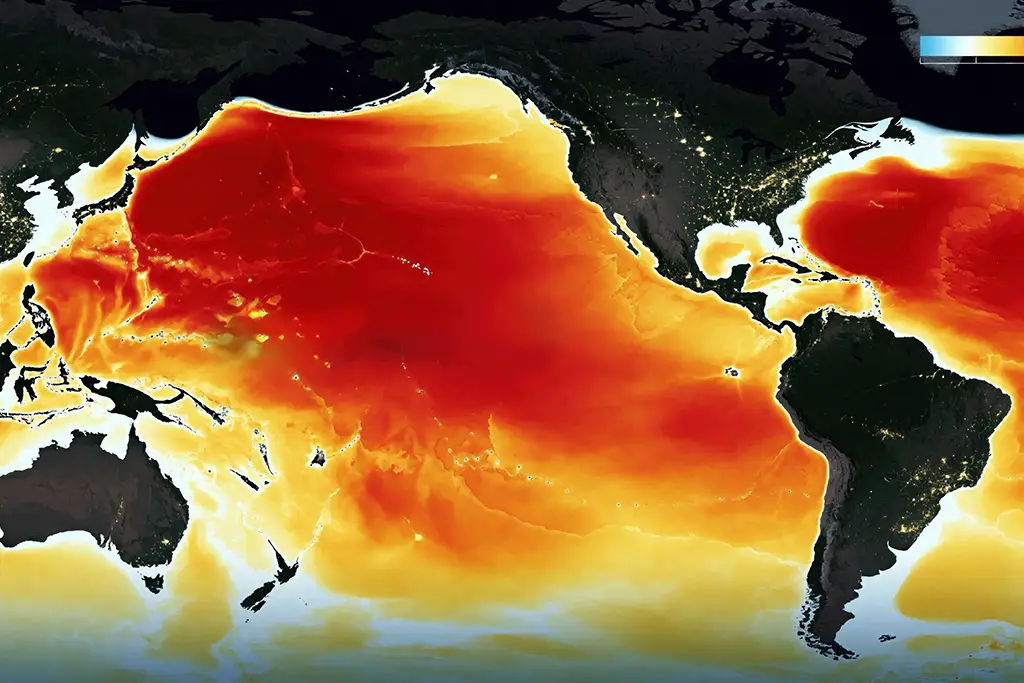
The National Oceanic and Atmospheric Administration (NOAA) predicts a record-setting Super El Niño in the United States this year. With this, shifting weather patterns are on the horizon for Colorado in the coming months.

While lead meteorologist Scott Handel emphasized that “no two El Niños are exactly the same,” there are some assumptions that can be made based on past El Niño events. An active winter is expected in Colorado, but a major snow season is not guaranteed. Historically, above-average snowfall takes place in the mountains, especially the San Juan Mountains.

The Front Range, on the other hand, may experience an increase in snowfall due to the large spring storms that El Niño can bring, but it is uncertain. If the subtropical jet stream moves north, Colorado could see a very wet winter. Conversely, if it remains south, the state may have a much less snowy season.

In lower elevations, warmer temperatures could reduce snowfall. These areas may experience rain instead, but nothing is definite.

Moreover, experts predict that winter may begin late but progress in activity later. Climate models point toward a busy mid-to-late winter, even extending to the spring season.


How to Winterize HOA Community

Given the variability that an El Niño Colorado winter brings, HOAs and condominiums must prepare for every possibility. In general, here are the best strategies for HOA winter preparation, as supplemented by Colorado’s own hazard-planning guidance.


1. Inspect Roofs and Drainage Systems

Before winter comes, boards should hire a professional to inspect the association’s roofs and drainage systems. For HOAs, the focus is more on association-managed properties, such as clubhouses, fitness centers, and other facilities. For condominiums and townhomes, there are more shared roofs and drainage systems to worry about.

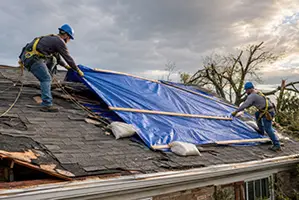
Inspection items should include roofs, gutters, downspouts, drainage, foundations, and other exterior components. Check ice dam-prone areas, identify and seal potential leaks, and look for signs of previous water intrusion. Address areas where snow tends to accumulate.


2. Prepare for Both Snow and Ice

A big part of HOA winter preparedness should address snow and ice. While snow is a variable with Super El Niño, it still helps to have a written plan for snow plowing, sidewalk clearing, deicing, and ice monitoring. Boards must also consider emergency access, fire-lane access, entryways, stairs, and parking lots.


3. Check Heating Systems Before Temperatures DropSuper El Niño Colorado
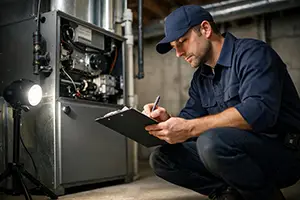
Communities with shared heating systems must prioritize maintenance and winterization. Furnaces, boilers, heating equipment, ventilation systems, and other components must undergo thorough inspection before the cold season.

The association should identify emergency heating procedures, equipment with a history of failure, and areas that are more prone to freezing. It is also essential to have backup power available at all times. Other than that, should systems fail, the board must have a provider for after-hours service.


4. Protect Pipes and Water Systems

When it comes to HOA winter preparation, frozen and burst pipes should always be part of the list. Exposed pipes are more likely to freeze and burst, so inspection and winterization are essential. Make sure to properly insulate these pipes and seal any drafts around the areas where the pipes sit. In case of a burst pipe, board members must know where the shutoff valves are located.


5. Review Snow Removal Contracts Now

Some associations wait until the first storm to check their snow removal contract, only to find that it doesn’t cover what the community needs. A big part of Colorado winter weather preparation is having a snow-removal vendor on standby at all times.

When reviewing the contract, make sure to check the trigger depth for service, response times, plowing and sidewalk responsibilities, deicing services, ice monitoring, snow relocation, emergency service, and communication procedures. If additional storms or services are required, the contract should also specify pricing models for them.


6. Inspect Trees and Landscaping

Snow, ice, and wind can cause branches to break off and trees to fall. These are clear safety hazards and can also damage private property. Proper HOA winter storm preparation includes inspecting trees that stand near buildings, sidewalks, parking areas, roads, utility lines, and community amenities.

If there are hazardous or diseased branches, make sure to prune them before the winter season. Board members can’t do this alone, not without the right expertise and equipment, so hiring a professional is necessary.


7. Check Emergency Supplies and Procedures

Every HOA winter emergency plan should include well-stocked supplies, clear procedures, and a list of important contacts. The association should regularly update contact information for its providers, including the management company, the snow contractor, plumbers, the HVAC contractor, electricians, the roofing contractor, tree service, the insurance carrier, and emergency services. Emergency supplies must include ice melts, flashlights, batteries, and backup equipment.


8. Review Insurance and DeductiblesEl Niño Colorado winter
Insurance plays a significant role in winter, especially when emergencies arise. Boards should take a good look at the association’s master insurance policy, particularly property coverage, general liability coverage, deductibles, and exclusions.

Some policies have separate wind or hail deductibles, while others also cover water damage claims. Reviewing insurance helps determine what the HOA is responsible for and what owners are responsible for. It also allows the board to get a grasp of the claims filing process.


9. Review the Reserve Fund Before Winter

The HOA’s reserve fund can come in handy when winter storms cause costly repairs. Roofs, drainage systems, sidewalks, heating systems, pavements, and other exterior components are most likely to experience damage. Boards must ensure the association has sufficient reserves to cover repairs or replacements if insurance coverage is inadequate.


10. Prepare for Unusual Temperature Swings

Super El Niño comes with unusual temperature swings. Because of this, HOAs and condos in Colorado must prepare for an ongoing rotation of snow, melting, refreezing, ice, and additional snow. A wet winter brings slippery walkways, drainage issues, roof leaks, ice dams, and damage from the freeze-thaw cycle.


11. Communicate Responsibilities to Homeowners

While the association is responsible for shared areas and common elements, it is not responsible for individual homes or units. Of course, that doesn’t mean the board must remain idle.

To prepare the whole community, boards should remind owners of their winter maintenance obligations. Even a simple notice works. This notice can include tips for winterization, instructions on how to report leaks or frozen pipes, and directions for emergency requests.


HOA Winter Maintenance Checklist

Here is a quick rundown of the tasks involved in HOA winter preparation:

  • Inspect roofs, gutters, drains, and exterior building components
  • Inspect heating systems and vulnerable plumbing
  • Confirm snow and ice removal contracts
  • Identify snow storage and emergency access areas
  • Inspect trees near buildings, roads, and utilities
  • Stock winter maintenance and emergency supplies
  • Review insurance policies and deductibles
  • Review reserve funding for components
  • Document known deficiencies before the season begins
  • Create procedures for frozen pipes, roof leaks, heating failures, and storm damage
  • Confirm contractor and emergency contact information
  • Tell homeowners what the association maintains and what owners are responsible for


An Uncertain Season

In Colorado, the forecasted Super El Niño has made it difficult for boards to plan for the winter season. With several variables at play, HOA winter preparation must account for every possibility. Dry snow is not a guarantee, and a more active freeze-thaw cycle may result in greater damage and more safety hazards. When in doubt, a professional HOA management company can help.

Westward360 is a trusted partner for HOAs and condo associations across the United States, including Colorado. To get started on expert association management, contact us today or request a proposal online!

What Can HOA Boards Do About Rising HOA Insurance Costs?

Rising HOA insurance rates are crippling association funds, leading to reduced coverage, higher dues, and budget shortfalls. As insurance is a must for many communities, boards are struggling to meet insurance requirements while still maintaining a healthy financial position. Fortunately, there are some strategies boards can employ to minimize the effects of insurance spikes.


Factors That Affect Rising HOA Insurance

Homeowners associations and condominiums are responsible for protecting their finances and physical assets. This typically comes in the form of insurance. In fact, many states require HOAs and condos to maintain adequate coverage.

Yet in recent years, insurance has become an expensive line item in most community budgets. The Foundation for Community Association Research discovered that 93% of managed associations have suffered an increase in insurance rates. Master policies have increased by 90.4% over a two-year period.

Premiums are rising, and coverage has decreased significantly. Carriers are even discontinuing service to community associations entirely, thereby limiting options and causing costs to spike even further.

When determining rates, carriers consider several factors, such as:

  • The type of community
  • The association’s governing documents
  • Total replacement cost
  • Deductibles and exclusions
  • The age of the building or assets
  • Square footage and number of units
  • Risk exposure and mitigation practices
  • Relevant geographic risks
  • Claims history
  • Amenities and facilities
  • The type of construction

Insurance premiums can vary greatly from one association to another. Two HOAs in the same area can have considerably different costs depending on their profiles.


What’s Causing High HOA Insurance Costs?

There are two main causes affecting insurance costs: inflation and severe weather events.

Inflation is rising rapidly, driving up the cost of construction materials and labor. As prices rise, claims are becoming more expensive for carriers, prompting them to raise insurance rates.

Weather events are also becoming more extreme and unpredictable. North America has been experiencing more frequent hurricanes, wildfires, and floods. These natural disasters are making carriers suffer significant losses.

When combined, inflation and weather have made it riskier for carriers to insure HOAs and condominiums. Those that still provide coverage are becoming more selective, implementing stricter underwriting standards.

Because of these factors, communities now face higher premiums, larger deductibles, more exclusions, and decreased coverage.


What Can Boards Do About Increasing HOA Insurance Costs?

Associations can cope with rising HOA insurance premiums by reviewing their coverage every year, maintaining strong insurance and property records, prioritizing preventive maintenance, budgeting for higher insurance costs, evaluating deductibles against HOA funds, shopping the insurance market carefully, communicating insurance costs with homeowners, and focusing on insurability (not just premiums).

Let’s discuss each strategy below.


1. Review Insurance Coverage Every Year

Boards must evaluate their HOA insurance policies annually. Waiting until the renewal date comes along may already be too late.

Regular reviews, particularly with an insurance professional, can help identify gaps in coverage and determine if the HOA is in a good financial position to accommodate the policy. The review should cover policy limits, exclusions, deductibles, replacement costs, and potential exposure risks.

Replacement costs are especially important. The value of buildings can change drastically as construction and labor costs rise. If an HOA uses an outdated replacement cost estimate, the carrier may require a substantial increase in coverage. This, in turn, can result in higher premiums.


2. Maintain Strong Insurance and Property Records

rising hoa insurance premiums

Now more than ever, insurance carriers look for documentation that shows how an HOA manages its property and mitigates risks. Boards should maintain clear and accurate records that they can easily provide when renewing their policy or filing a claim.

While records can vary from one community to another, it is generally recommended to maintain the following:

  • Maintenance history and completed repairs
  • Roof replacements and inspections
  • Plumbing and electrical upgrades
  • Balcony inspections and repairs
  • Fire alarm and sprinkler inspections
  • Safety inspections
  • Wildfire mitigation and defensible space work
  • Vendor contracts
  • Reserve studies
  • Incident and claims reports
  • Meeting minutes related to major maintenance or risk management decisions


3. Prioritize Preventive Maintenance

Maintenance plays a significant role in minimizing property damage and liability claims. Boards should conduct regular inspections for all components and maintain records of these checks. A review of the association’s claims history can also help identify recurring problems or patterns.

For example, if the HOA consistently files water-damage claims, it may indicate a larger plumbing issue. Addressing the root cause can prevent breakdowns and minimize future claims. Carriers feel more confident in providing coverage when the association shows its commitment to preventive maintenance.


4. Budget for Higher Insurance Costs

Boards have no direct influence over rising HOA insurance, so it’s important to focus on what they can control — and the budget is one of them. Since insurance is required for most associations, boards must include it in their long-term financial planning. It’s best to assume that insurance will continue to rise rather than hope it will soon level off.

Every new year’s budget should account for a higher premium than the last. This gives the board a cushion of sorts, allowing dues to adjust accordingly and making special assessments less likely.


5. Evaluate Deductibles Against HOA Funds

Higher deductibles allow for lower premiums, but the board must consider whether the association can comfortably cover the amount after a loss. It may seem prudent to raise deductibles now, but an HOA can’t pay for them after a loss if its reserve or operating accounts are inadequate.

When evaluating insurance policies, boards should compare potential deductibles with available funds. Moreover, boards should verify that homeowners have sufficient loss assessment coverage on their respective HO-6 policies.


6. Shop the Insurance Market Carefully

While sticking with the same carrier might show loyalty, it can trap an association into a corner. Board members should shop around every now and then to look for more competitive rates. If the current carrier raises its premiums, it is worth checking what other carriers in the market charge for the same policy.

Of course, price shouldn’t be the sole consideration. Boards should also compare deductibles, exclusions, claims service, and coverage.


7. Communicate Insurance Costs with Homeowners

increasing hoa insurance costs

Insurance is often one of the largest line items in an HOA budget, contributing to higher dues. Homeowners may protest the expense, but this is usually because they don’t quite understand what’s going on behind the scenes.

Boards should explain the changes in insurance costs and the factors affecting premiums. It is also a good idea to communicate what steps the HOA is taking to manage its insurance expenses. Communication helps limit pushback and reduce delinquencies.

Additionally, boards must inform owners of their own insurance responsibilities. In general, they must each carry an HO-6 policy with adequate loss assessment coverage.


8. Focus on Insurability, Not Just Premiums

While the premium itself is important, boards should not focus only on that. Insurability is the chief concern, with factors such as claims history, maintenance, building age and condition, and financial planning all playing a role. Market conditions are beyond the board’s control, so it’s better to focus on addressing preventable risks and keeping the community attractive to carriers.


The Best Way Forward

Whether they like it or not, association boards must deal with rising HOA insurance costs. Eliminating insurance from the budget altogether isn’t an option, but preparation and risk mitigation can help make insurance rates more manageable. When in doubt, consulting an HOA management company or insurance professional is recommended.

Westward360 is a trusted partner for HOAs and condo associations across the United States. To get started on expert association management, contact us today or request a proposal online!

Is Your HOA Reserve Funds Enough?

Community associations rely on HOA reserve funds for major repairs and replacements. Yet, far too often, these reserves are nowhere near the right level of funding. Healthy reserves prepare the association for the future, and boards can gauge whether or not they have enough funding by following simple practices.


What are HOA Reserve Funds?

The homeowners association reserve fund consists of money used to pay for major repairs and replacements once capital components reach the end of their useful life. It essentially functions as a savings account, set aside for long-term expenses.

Reserves play a crucial role in preserving the association’s finances and assets. Without properly funded reserves, boards would need to defer maintenance, levy special assessments, significantly raise dues, or take out a loan to cover the shortfall.


What are the HOA Reserve Requirements?

State laws and the governing documents determine if an association is required to fund reserves.

Currently, only 12 states require condo associations to fund reserves. These are Connecticut, Delaware, Florida, Hawaii, Illinois, Maryland, Massachusetts, Michigan, Minnesota, Nevada, Ohio, and Oregon. Condominiums have broader maintenance responsibilities because they have more shared elements.

Apart from HOA reserve fund laws, board members must also review their CC&Rs and bylaws. Even if state laws are silent, the governing documents may mandate reserve funding.


What Can HOA Reserve Funds Be Used For?

Depending on the governing documents, an association can generally use HOA reserve funding to cover repairs and replacements of major components or infrastructure.

Examples include:

  • Fixing or replacing roofs on shared buildings such as clubhouses or security gates
  • Repaving community parking lots, private streets, and shared driveways
  • Resurfacing community swimming pools
  • Upgrading playground equipment
  • Replacing shared HVAC systems, elevators, or fencing in common areas

That said, associations generally can’t use reserve funds to pay for operating expenses, such as routine maintenance and management fees. That’s what the operating fund is for.


What is the Right HOA Reserve Funding Percent?

Ideally, an association should aim to keep its reserves between 70% and 100% funded at all times.

There is no exact dollar amount that works for all associations. Every community has different needs, infrastructure, and risks. Even when two buildings are constructed exactly alike, they can differ in wear, damage, and long-term use.

To determine the right funding level, associations must conduct a reserve study. This study identifies the major capital components of the HOA, how much useful life they have remaining, and the cost to repair or replace them. That said, the HOA reserve rule of thumb is to have at least 70% of its funding needs covered at any time.


What are the HOA Reserve Funding Strategies?

There are three funding strategies for HOA reserves: full funding, threshold funding, and baseline funding. Let’s break these down below.


1. Full Funding Strategyhoa reserve funding

A full funding strategy aims to keep the reserve balance at or near 100% of the calculated amount in the reserve study.

This strategy offers maximum protection, as it ensures that the association can cover all of its reserve costs. Of course, it may require higher reserve contributions over a shorter period.


2. Threshold Funding Strategy

A threshold funding strategy establishes a minimum percentage that’s considered safe for a reserve balance. Typically, this is 70% of the fully funded amount as indicated in the reserve study.

Threshold funding balances risk mitigation and affordability for homeowners in terms of reserve contributions. For this reason, it is the most favored funding strategy.


3. Baseline Funding

A baseline funding strategy sets contributions just high enough to keep the reserve balance from reaching zero at any time. This strategy keeps HOA dues low, but it doesn’t leave much room for error or unexpected costs. There is also a higher risk of special assessments.


Drawbacks of Underfunded HOA Reserves

When an association lacks adequate reserves, it can face consequences.

The need for major repairs and replacements will eventually catch up. When that time comes, if the HOA doesn’t have sufficient reserves, it will have to levy large special assessments or significantly raise dues. Another option is to take out a loan from a bank, but that’s only a temporary fix. Owners must still be held responsible for repayment.

Apart from the financial impact, underfunded reserves can also have legal implications. Board members have a fiduciary duty to maintain the association. Poor reserve planning and the resulting inability to repair or replace components may constitute a breach of this duty. Owners may take legal action against the HOA and even the board members themselves.

Without money, boards will need to defer major repairs and replacements. This can cause irreversible damage and deterioration, thereby lowering curb appeal and property values. In the end, homeowners won’t get a satisfactory return on their investment.


How are HOA Reserves Funded?

Reserves are funded by the homeowners, with a portion of their regular dues allocated as the HOA reserve contribution.

Board members rely on an updated reserve study to determine how much each owner must contribute to the reserves. Gradual contributions through regular dues are the norm, but the board may turn to large special assessments if its reserves are underfunded and a major repair is scheduled soon.


Are HOA Reserve Funds Taxable?

In general, reserve contributions are not taxable income, but the interest or investment earnings on those funds are.

If an HOA wishes to prevent the IRS from classifying reserves as taxable income, it should follow specific accounting practices. These include keeping the reserves completely separate from the operating funds and only spending the reserves on major capital repairs or replacements.


Best Practices for HOA Reserve Fund Management

Managing the reserves requires discipline, compliance, and expertise. Professional HOA management can help with reserve planning and oversight, but self-managed boards must rely on the following tips.


1. Keep Accounts Separatehoa reserves rule of thumb

Associations must always keep the HOA reserve account and operating account separate. Commingling funds not only makes it harder to track money but can also render the reserves taxable. Remember that operating funds pay for day-to-day expenses, while reserve funds cover major capital repairs and replacements.


2. Conduct a Reserve Study

A reserve study can determine the condition of each major component, its remaining useful life, and the total repair or replacement cost. It also comes with a funding plan that ensures an HOA has sufficient reserves.

Several states require associations to perform a reserve study every few years. In Virginia, for instance, HOAs must conduct this study once every five years to account for economic changes and evolving market projections (Section 55.1-1826). Even without a statutory requirement, boards would be wise to hire a professional reserve specialist to conduct this study.


3. Invest Wisely

Since reserves tend to remain stagnant for several years, associations may wish to invest them to maximize returns. That said, when choosing investment plans, the board must always prioritize safety and liquidity while keeping FDIC insurance limits in mind.


The Best Way Forward

The HOA reserve funds play an essential role in long-term capital planning and financial stability. Board members must maintain a healthy funding level and employ the industry’s best practices. When in doubt, hiring an HOA management company can help.

Westward360 is a trusted partner for HOAs and condo associations across the United States. For expert association management, contact us today or request a proposal online!

HOA Special Assessment: When Reserves Aren’t Enough

An HOA special assessment can come in handy during times of financial crisis. That said, there are certain requirements, procedures, and limitations involved. Board members must understand how special assessments work to ensure compliance and avoid liability.


What is an HOA Special Assessment?

A special assessment is an additional fee that an HOA collects from homeowners on top of their regular dues.

Unlike dues, HOA special assessments are one-time charges. This means that they do not recur, only coming up if the association requires an extra cash injection. The purpose of a special assessment is to pay for unexpected costs that the operating budget, reserve fund, or insurance can’t cover.


Can an HOA Levy Special Assessments?

The answer depends on state laws and the association’s governing documents.

Some state laws explicitly give HOAs and condominiums the authority to levy special assessments. One such example is Virginia. Under Section 55.1-1825 of the Property Owners’ Association Act, an HOA may impose an additional assessment if it serves the association’s best interests and the purpose is primarily for common area maintenance and upkeep.

When state laws are silent, board members must refer to their CC&Rs and bylaws. Even if state laws grant express authority, many governing documents enforce additional requirements or procedures that boards must follow when levying HOA special assessments.


What is an HOA Special Assessment For?hoa special assessments

In general, an HOA special assessment is used to cover emergency repairs, budget deficits, capital improvements, or underfunded reserves.

  • Emergency Repairs. If insurance doesn’t cover a repair caused by an emergency, such as a natural disaster, a special assessment can step in.
  • Budget Deficits. A special assessment can cover shortfalls in the budget caused by unexpected costs or high delinquency rates.
  • Capital Improvements. When the HOA needs to fund a large project, such as a renovation, it may turn to special assessments if its current funds are inadequate.
  • Underfunded Reserves. Associations can use special assessments to bridge the gap when the reserve account isn’t at a healthy funding level.

While these are common examples, boards must check their governing documents. Some CC&Rs and bylaws limit what associations can use special assessments for.


Is There an HOA Special Assessment Limit?

It depends on state laws and the association’s governing documents. Most states don’t impose a ceiling for special assessments, instead letting associations rely on their CC&Rs and bylaws.

One notable exception is California. Under Civil Code Section 5605, an HOA board can impose a special assessment of up to 5% of the association’s budgeted gross expenses for the current fiscal year without member approval, even if the governing documents set different limits.

Some CC&Rs and bylaws place a percentage limit on special assessments, while others have a strict dollar cap. There are also those that require membership approval when exceeding a certain percentage or amount.


HOA Special Assessment Rules to Know

Requirements and procedures for HOA special assessments can vary from one association to another. It is important to check the governing documents for specific guidance.


Required Vote (Board or Membership)

Many CC&Rs and bylaws require a vote of approval to pass a special assessment, either from the HOA board or the entire membership. Board approval is easier to obtain, as it usually requires only a majority vote of the directors.

Membership approval, on the other hand, is trickier. Most governing documents require a supermajority or a specific voting threshold to approve a special assessment. Since this assessment is an additional charge, boards often struggle to secure the necessary votes, as most owners don’t want to pay another fee.

Still, education is key. If owners understand the purpose of the assessment and how it will benefit the community as a whole, they are more likely to support the proposal.

Of course, there is typically an exception that allows the board to bypass a vote. If the expense addresses an emergency safety or health issue, approval may not be needed.


HOA Special Assessment Notice

Depending on the governing documents, associations must give homeowners formal written notice of the special assessment. This notice must detail the cost of the assessment, the reason for it, and the payment deadline. While timeframes can vary, most CC&Rs and bylaws require 30 to 60 days’ advance notice.


Calculations

In some communities, the special assessment must address a funding cap. This is calculated by subtracting the insurance payouts and available reserve funds from the overall cost of the project.


Cost Allocation

Depending on the CC&Rs and bylaws, the allocation of the assessment follows a specific formula. Most communities split the cost equally among all homeowners. Meanwhile, others allocate the cost based on property size or type.


Payment Termshoa special assessment rules

Associations often allow owners to pay their assessments either in a lump sum or in installments over several months. It usually depends on the association’s governing documents and the urgency of the need.


Designated Use

Most governing documents require the board to use the special assessment solely for the proposed or communicated purpose. For example, if the board approved the special assessment for a landscaping project, it can’t use the surplus to fund a community event.


How Often Should an HOA Levy a Special Assessment?

A healthy HOA should rarely impose a special assessment on its residents.

Associations are responsible for financial planning and management. This includes projecting operating costs and allocating appropriate reserves based on a reserve study. If the budget doesn’t fall short and the reserves can cover all major projects, then there shouldn’t be a need for HOA special assessments. The key is to make prudent financial decisions.

If an HOA frequently charges additional assessments, it may indicate a bigger problem. The board should investigate the cause and address it at its root. For example, if special assessments are consistently triggered by unexpected repairs, it could be traced back to a lack of preventive maintenance. Similarly, an outdated reserve study with obsolete funding recommendations may result in underfunded reserves.


Is an HOA Special Assessment Tax Deductible?

No, special assessments that an HOA collects are generally not considered taxable income. This means that the association doesn’t pay income tax on these charges.

That said, there is a condition. To remain non-taxable, the association must use the special assessment for exempt functions, such as managing and maintaining HOA-owned property. This includes using the money on repairs or capital improvements.


Treading Carefully

When used correctly, an HOA special assessment can be a practical financial tool. This additional charge can help improve cash flow and keep an association financially solvent. That said, it comes with certain limitations and requirements that can vary from one community to another. Reviewing state laws and governing documents can help ensure compliance.

Westward360 is a trusted partner for HOAs and condo associations across the United States. For expert association management, contact us today or request a proposal online!

WWT Favicon

Use the search bar below to help locate what you are looking for on our site.